
For an executive condominium purchase, identify the project’s land-sale cohort before applying an income ceiling, minimum occupation period or payment scheme. The May and August 2026 changes use different cut-off dates. A project’s marketing launch year alone does not identify all the rules that apply.
Two policy dates to keep separate
The MND announcement of 8 May 2026 applies its changes to EC Government Land Sale sites with tender closing dates on or after that date. These include a 10-year MOP, removal of the Deferred Payment Scheme and a 90% first-timer quota with a two-year priority period. Earlier sites remain on the earlier framework.
A separate HDB announcement on 23 August 2026 raises the new-EC monthly household income ceiling from S$16,000 to S$18,000 for new units in projects with land-sale tender closing dates on or after 24 August 2026. It expressly excludes balance units in existing ECs and new units in projects with tenders awarded before 24 August.
These two changes should not be combined into a single rule for every launch advertised in 2026 or 2027. Ask which cohort the specific project belongs to, then assess your household under its eligibility conditions. The income ceiling is only one part of that assessment.
Count the occupation period from TOP
HDB’s post-purchase conditions state that the MOP is computed from the Temporary Occupation Permit date. The applicable period is 10 years for projects whose land sales tender closed on or after 8 May 2026, and five years for other projects. Booking during construction does not start that clock.
MND describes the earlier framework as allowing open-market sales to Singapore citizens and permanent residents after five years, with sales to any buyer after the tenth year. For the new cohort, those milestones move to ten and fifteen years respectively. The widening buyer pool does not guarantee a price increase or an easy exit.
HDB permits whole-unit renting only after the MOP. Renting bedrooms during the MOP has registration and notification requirements; it should not be treated as unrestricted whole-home letting. If rental income is essential to the financing plan, establish that the intended arrangement is permitted before relying on it.
Plan an existing-flat sale around key collection
HDB says anyone listed in the EC application with an interest in an HDB flat must dispose of that interest within six months from collection of the EC keys, measured by legal completion of the disposal. This is different from assuming the deadline always runs from the project’s TOP.
Map the EC payments, sale completion and moving dates on one calendar. A delayed flat sale can affect the funds available for the next payment even when the EC remains affordable over the longer term. For legal advice on the proposed sale sequence or contract, LovelyHomes can arrange a property-lawyer introduction.
Build a payment plan that adds to 100%
Use the developer’s actual contractual schedule and bank assessment. A generic table with invented construction dates is a poor substitute: progress payments depend on the agreed scheme and the relevant milestones.
Budget illustration: on a hypothetical S$1.5 million purchase, an assumed 75% bank loan is S$1,125,000 and the amount outside that loan is S$375,000. A 5% cash component would be S$75,000, leaving S$300,000 to be funded by eligible CPF and/or cash. This illustration excludes stamp duties, legal costs and other expenses and does not establish an approved loan or the dates each amount is payable.
The MoneySense affordability guide explains that borrowing depends on assessment, outstanding loans, age and tenure. An income ceiling does not mean the household can borrow enough for every unit below a chosen price.
Keep tenure and resale expectations realistic
Strata title describes ownership within a development; it does not make the land freehold. Read the project’s stated tenure and lease particulars. For example, CDL Homes lists the forthcoming Solano Grand and Wynwood Grand as 99-year developments.
Use our Solano Grand and Wynwood Grand guides to compare the projects, then request the applicable eligibility pack, payment schedule and unit quotation. The right EC is one whose location, holding period and funding plan fit the household, with a resale plan that works without an assumed appreciation windfall.
Corrected 14 November 2026: removed the freehold claim, launch-based ownership clock, blanket income/MOP rules and the payment table that exceeded 100%. Replaced unsupported grant, tax and resale-return claims with project-cohort and funding checks. Policy checked on the same date; individual eligibility remains subject to assessment.
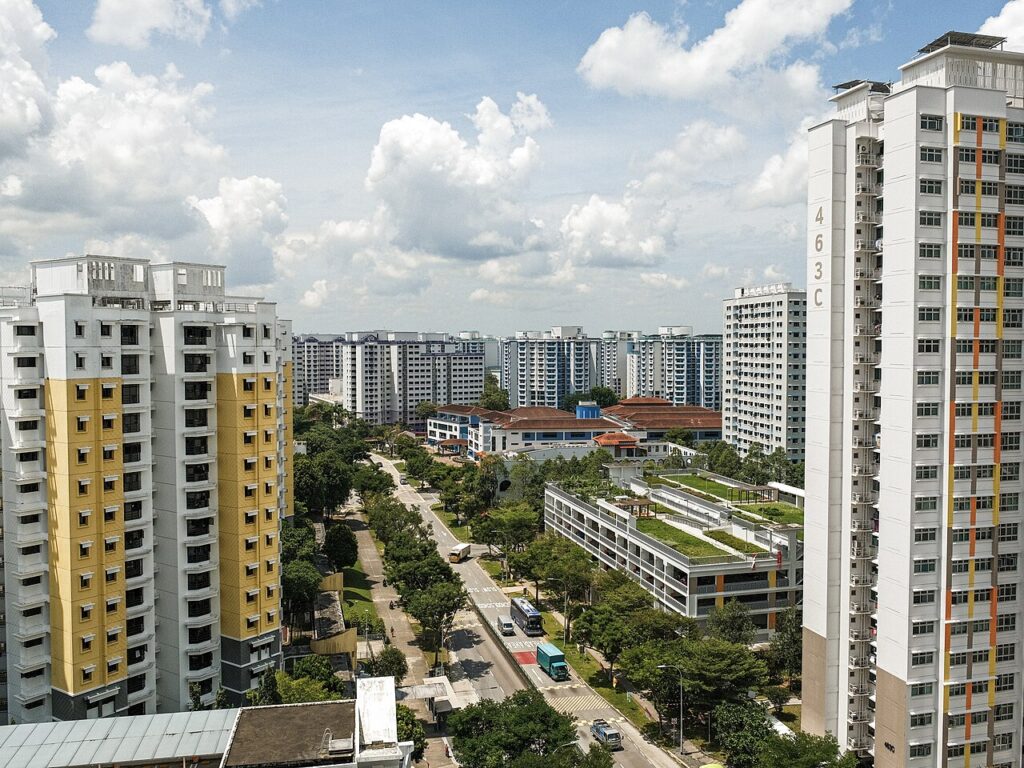
Archive housing photograph for context, not a photograph of the reviewed launch. HDB flats along Sembawang Drive (photographed 2024). Photo: Brhb25. Source (https://commons.wikimedia.org/wiki/File:HDB_flats_along_Sembawang_Drive.jpg) · CC BY-SA 4.0 (https://creativecommons.org/licenses/by-sa/4.0). Resized and displayed cropped.
Need a brochure, price list or professional introduction?
Contact Lin Xuan at 82222556 or Ade at 81888871 or Benn at 83218774 for the full project brochure, latest available price list, a viewing, or introductions to bankers who can help you compare home-loan rates and packages to find the best available option for your needs. If you need legal advice on a property purchase, sale or tenancy, we can also put you in touch with property lawyers.
WhatsApp Lin Xuan | WhatsApp Ade. Let us know the project or property question you would like help with. Prices and availability are subject to developer confirmation, while loan terms and approval are determined by the bank.
Lin Xuan: ONG LIN XUAN, CEA registration R069812H. Ade: CHUA MUAY MUAY (ADE CHUA), CEA registration R014252F. ERA REALTY NETWORK PTE LTD, estate agent licence L3002382K.
Benn: TAN JUN FENG, BENNEDICT (BENNEDICT TAN), CEA registration R058941E. PROPNEX REALTY PTE. LTD., estate agent licence L3008022J.