⚡ Quick Answer , Singapore Shoebox Apartments 2026
- Shoebox apartments are private residential units of 500 square feet (≈46 sqm) or smaller , a threshold popularised by market convention, though URA’s formal classification uses 50 sqm.
- Shoebox units command a higher PSF than standard-sized apartments but a lower absolute ticket price, making them accessible to first-time investors and singles.
- Gross rental yields on shoebox units in Singapore typically run at 4–5% per annum, above the 3–4% average for standard-sized condominiums , but this headline figure must be adjusted for higher vacancy risk and ABSD cost for investors.
- URA progressively tightened rules on small units from 2012; the latest 2023 guidelines require developers to maintain an average unit size of at least 85 sqm for new private residential projects, effectively reducing new shoebox supply.
- Investors buying a shoebox as a second property pay ABSD of 20% (Singapore Citizens) or 30% (Permanent Residents) , on top of BSD , making the breakeven rental yield calculation critical.
- Capital appreciation for shoebox units has historically been uneven: strong PSF gains but compressed absolute gains vs larger units, with liquidity at resale dependent on investor demand.
- For own-stay buyers, liveability constraints , limited storage, small bedrooms, noise in dense-unit buildings , must be weighed against the lower quantum.
What Is a Shoebox Apartment in Singapore?
There is no single legal definition of a “shoebox apartment” in Singapore. The term is used informally by the market to describe private residential units at or below approximately 500 square feet (about 46 square metres). The Urban Redevelopment Authority (URA), which oversees private residential development guidelines, uses 50 sqm (538 sqft) as its internal reference for small-format units in regulatory communications, though this threshold has evolved over time.
Shoebox units are typically studios or 1-bedroom configurations, though some developers have produced compact 2-bedroom units within the 500 sqft envelope by using convertible furniture, loft mezzanines, or Japanese-inspired spatial planning. They are found across the island but are most commonly associated with inner-city and RCR locations where land cost makes compact units the economically viable product.
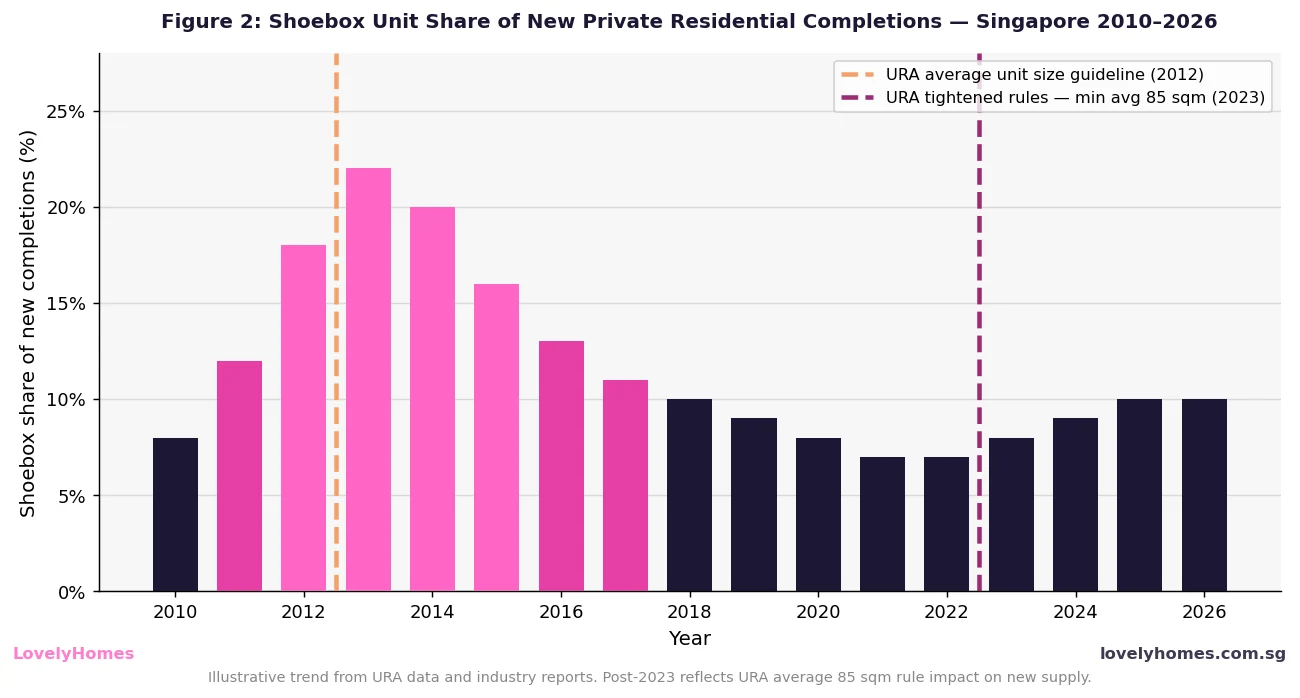
The category rose to prominence between 2008 and 2013, when a wave of developer-launched small-format projects capitalised on low absolute quantum (frequently below S$1 million per unit) to appeal to a broad investor base. URA responded in 2012 and again in 2023 with guidelines designed to moderate the proliferation of very small units, citing liveability and urbanistic quality concerns.
URA’s Regulatory Response , From 2012 to 2023
The surge in shoebox launches between 2009 and 2012 prompted URA to introduce its first formal guidelines restricting small units in July 2012. The 2012 rules established that for private residential developments outside the Central Area, developers must achieve an average unit size of at least 70 sqm across the project. This did not ban shoebox units outright but required developers to balance them with larger units, moderating the share of sub-500 sqft apartments in new launches.
Within the Central Area (broadly the CCR and parts of RCR), no average unit size requirement initially applied, which is why shoebox and micro-unit supply remained more prevalent in Districts 1–4 and parts of Districts 9 and 10.
In 2023, URA tightened the rules further, raising the required average unit size from 70 sqm to 85 sqm and extending the guideline’s geographic scope. This substantially reduced the viability of large shoebox-heavy projects for developers and has contributed to the declining share of sub-500 sqft units in new private residential completions since 2022.
Price Dynamics , PSF Premium vs Absolute Value
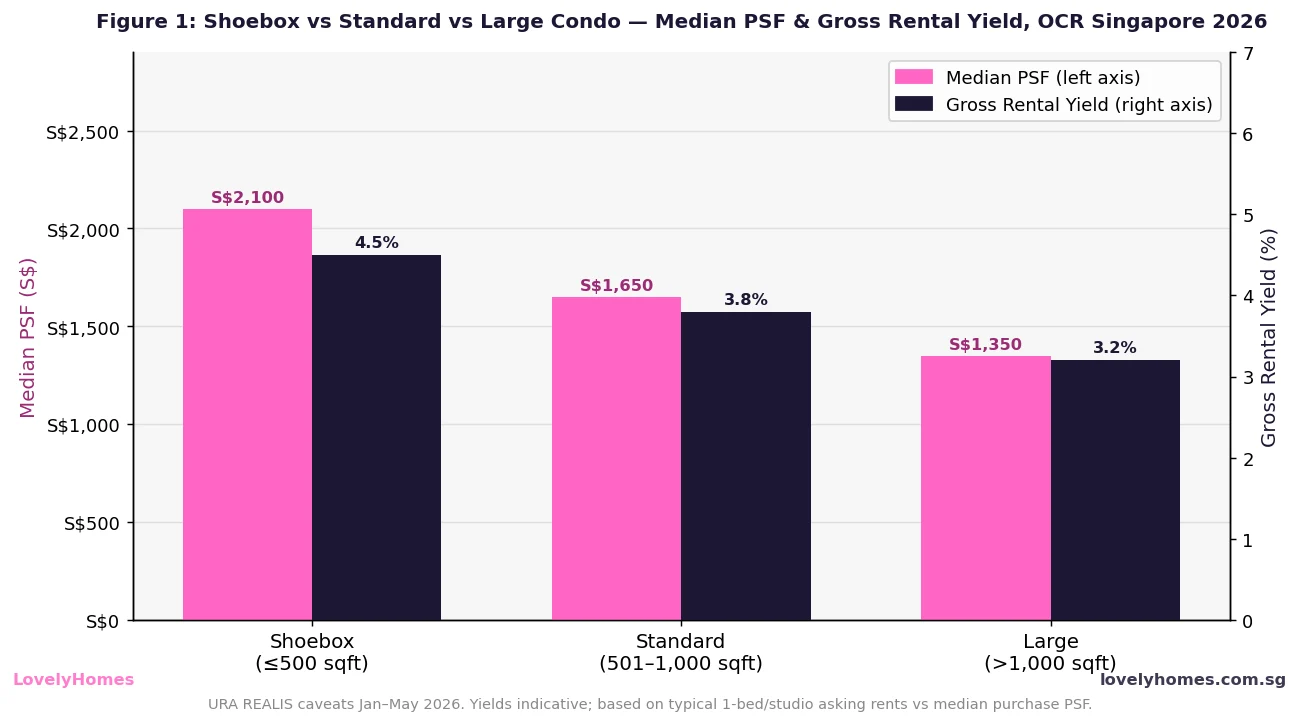
The shoebox paradox is that these units carry the highest PSF in any given development or market segment, yet the lowest absolute ticket price. In OCR markets as at mid-2026, a shoebox studio of 400 sqft might trade at S$2,000–S$2,200 PSF (ticket price S$800,000–S$880,000), while a 1,000 sqft 3-bedroom in the same estate might trade at S$1,500–S$1,600 PSF (ticket S$1.5M–S$1.6M).
This PSF premium reflects the unit’s rental utility per sqft , a studio rents for a disproportionately high amount relative to its area , and the lower absolute quantum that widens the eligible buyer and tenant pool. However, it also means that shoebox units can be harder to sell in a down market because their primary buyers are investors, and investor sentiment is highly sensitive to ABSD and interest rate cycles.
Capital appreciation history is mixed. Shoebox condominiums launched in 2009–2011 in inner-city locations (Districts 2, 3, 8, 12) have generally appreciated substantially in PSF terms, particularly where the surrounding area has undergone urban renewal. However, shoebox projects in suburban OCR locations have shown more muted gains, constrained by competition from larger new launches at comparable ticket prices and the structural preference of family buyers for standard-sized units.
Rental Yield , The Investor’s Core Metric
Gross rental yield on shoebox apartments in Singapore typically runs at 4.0–5.0% per annum in 2026, above the 3.5–4.0% average for standard-sized condominiums in OCR. This yield premium reflects the high demand from singles, young expatriates, and corporate tenants seeking short-stay or transit accommodation close to business districts or MRT nodes.
However, several factors compress the net yield to well below the gross headline:
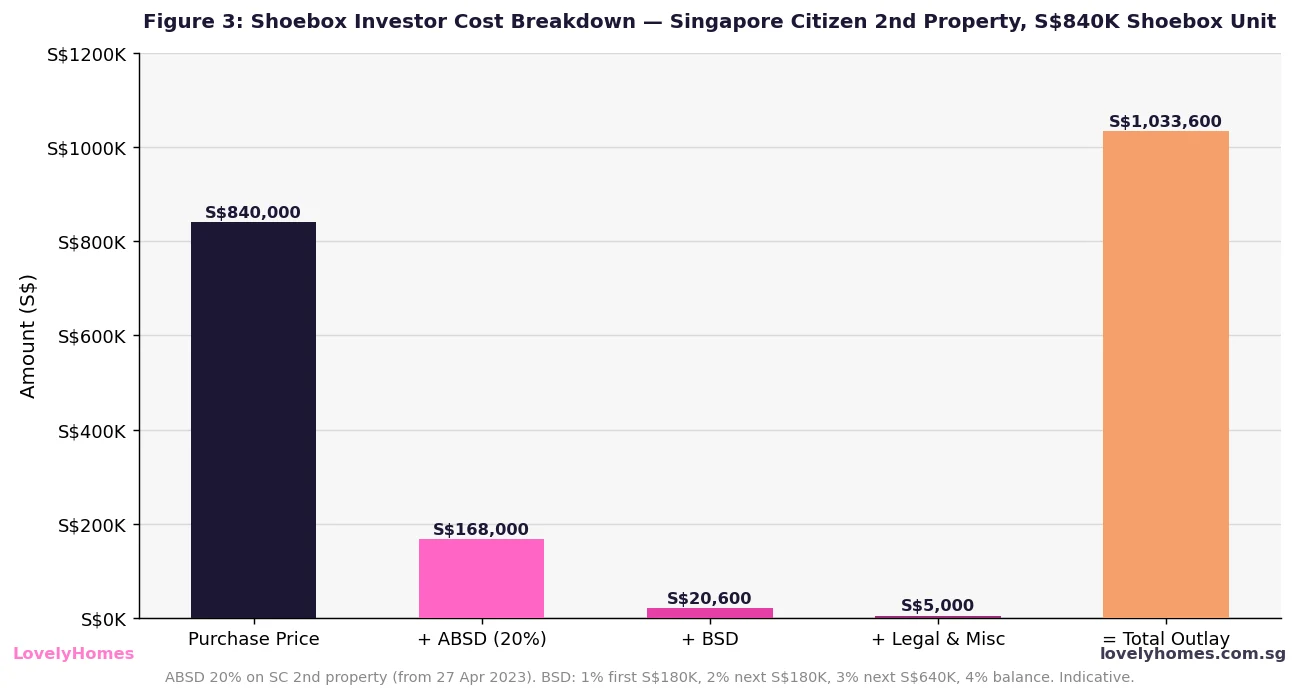
- ABSD cost: Investors paying 20% ABSD on a S$840,000 unit add S$168,000 to the acquisition cost. At S$3,500/mth gross rent (S$42,000 p.a.), the ABSD alone consumes four full years of gross rental income before any operating cost is counted.
- Vacancy risk: Small units, particularly studios, can face vacancy between tenancies. A 2-month vacancy per year reduces effective annual income by 17%.
- Property tax and maintenance: Annual Value (AV) on rental property incurs a higher progressive property tax rate (from 12% to 36% on AV above S$30,000 for non-owner-occupied property). Maintenance fees, property management, and periodic furniture/appliance replacement further erode net returns.
- Financing cost: At a 3.5% bank rate on 75% LTV, interest on a S$630,000 loan costs approximately S$22,050 p.a., consuming more than half the gross rent.
Summary: Shoebox vs Standard-Sized Condo , Key Metrics
| Factor | Shoebox (≤500 sqft) | Standard (500–1,000 sqft) | Large (>1,000 sqft) |
|---|---|---|---|
| Median PSF (OCR, 2026) | ~S$2,100 | ~S$1,650 | ~S$1,350 |
| Typical ticket price | S$700K–S$1.1M | S$1.0M–S$1.7M | S$1.5M–S$3M+ |
| Gross rental yield | 4.0–5.0% | 3.5–4.0% | 3.0–3.5% |
| ABSD (SC 2nd property) | 20% on full price | 20% on full price | 20% on full price |
| Primary buyer profile | Investors; singles; young expats | Families; HDB upgraders | Families; owner-occupiers |
| CPF usability | Full (if lease ≥ age 95 rule) | Full | Full |
| Liveability (own-stay) | Tight; limited storage; noisy corridors | Comfortable for 1–2 pax | Family-suitable |
| URA new supply rules | Restricted (85 sqm avg rule) | Standard | Standard |
| Resale liquidity | Investor-dependent; can be thin | Broad buyer pool | Broad; family-oriented |
📄 Worked Example: Ms Teo , Shoebox Investor, 2nd Property
Ms Teo (Singapore Citizen, aged 42) already owns an HDB flat and wishes to buy a shoebox studio near Queenstown MRT as an investment. She identifies a 420 sqft studio at S$838,000 (approximately S$1,995 PSF).
Acquisition costs:
- Purchase price: S$838,000
- ABSD (SC, 2nd property, 20%): S$167,600 , must be paid in cash within 14 days of exercising the OTP; cannot use CPF
- BSD: 1% × S$180,000 + 2% × S$180,000 + 3% × S$478,000 = S$1,800 + S$3,600 + S$14,340 = S$19,740 (payable via CPF OA)
- Legal fees: ~S$3,000–S$4,500
- Total acquisition outlay: ≈ S$1,030,000
Financing:
- Bank loan (75% LTV, first loan on this property): S$628,500 at 3.5% p.a. over 25 years → S$3,145/mth
- TDSR check: Ms Teo’s monthly income S$9,500 (declared); TDSR 33.1% PASS (monthly obligations S$3,145 / S$9,500)
- Downpayment: S$209,500 (25%) , S$19,740 BSD via CPF OA, balance cash/CPF. ABSD S$167,600 cash
Rental income & yield:
- Monthly rent: S$3,400 (market estimate for 1-bed studio near Queenstown, 2026)
- Gross yield: S$40,800 / S$838,000 = 4.87% p.a.
- Less: bank interest S$22,000 p.a. + property tax ~S$2,800 + maintenance S$2,400 + vacancy buffer S$3,400 = S$30,600
- Net annual cashflow (pre-tax): S$40,800 − S$30,600 − S$37,740 principal (loan repayment non-interest) ≈ breakeven in cash terms; ABSD recovery takes ~4.5 years of gross rent
Verdict: Shoebox investing remains viable for Ms Teo if she can hold for at least 8–10 years to absorb the ABSD drag and capture capital appreciation. In a softer rental market, the net yield compresses significantly. The strategy works best when the unit is near an MRT interchange in an area with strong expat or young professional demand.
Why Shoebox Apartments Matter in Singapore’s Housing Landscape
Shoebox apartments fulfil a genuine market need that Singapore’s housing typology does not otherwise serve well. The public housing (HDB) system does not offer units below 2-room BTO flats (approximately 36–45 sqm, not available for purchase on the open market except under restricted resale conditions). For singles who do not qualify for HDB purchase, do not wish to rent long-term, and cannot afford a standard-sized private unit, the shoebox condo represents the primary owner-occupier option at a sub-S$1M quantum.
From a planning perspective, URA’s tightening of unit size guidelines reflects a tension between market demand (investors and singles want small, affordable units) and planning ideals (cities function better with diverse household sizes, and very small units create density without the amenity space to support it). Singapore’s approach has been to moderate rather than prohibit, allowing the market to produce some shoebox supply while ensuring developers cannot build entire estates of sub-50 sqm micro-units.
What Might Come Next , Shoebox Policy and Market Outlook (Speculative)
This section reflects analyst views and market signals, not confirmed government policy.
The 2023 tightening of average unit size requirements to 85 sqm will take time to fully filter through the pipeline; projects approved under earlier rules may still produce shoebox units over the next two to three years. Over the medium term, reducing new shoebox supply while rental demand from singles and young professionals remains firm should sustain the rental yield premium on existing shoebox stock , a favourable dynamic for current investors.
However, rising interest rates from 2022–2024 and the significant ABSD burden on investor purchases have already moderated investment demand for this segment. If future cooling measure reviews reduce ABSD on second properties (which some analysts argue is overdue given its dampening effect on market liquidity), shoebox demand would likely recover sharply. Conversely, any further tightening of CPF rules for small units or a slowdown in expatriate inflows would reduce the rental demand underpinning yields.
For buyers considering a shoebox as an owner-occupied first home, URA’s supply tightening may paradoxically improve their medium-term resale prospects: a shrinking pool of new shoebox completions sustains demand for well-located existing stock.
Frequently Asked Questions , Shoebox Apartments Singapore 2026
What is the URA definition of a shoebox apartment?
URA does not publish a single public “shoebox” definition but has used 50 sqm (538 sqft) as a reference threshold for small-format units in its regulatory guidelines, including the 2012 average unit size restrictions. The market typically uses 500 sqft (46.5 sqm) as the informal shoebox boundary. Anything at or below this size , studios, micro-studios, and some compact 1-bedroom configurations , is colloquially described as a shoebox. Units between 501 and 650 sqft are often called “compact” apartments; these do not face the same buyer scepticism but are also subject to URA’s average unit size rules at the developer level.
Can a Singapore Permanent Resident buy a shoebox condo?
Yes. Singapore Permanent Residents (SPRs) can buy private residential condominiums, including shoebox units, without restriction (HDB flats have different rules). However, SPRs purchasing a second residential property , including a first private property if they already own an HDB , pay ABSD of 30%, compared to 20% for Singapore Citizens. A SPR buying a shoebox at S$840,000 as a second property would incur ABSD of S$252,000, materially altering the investment economics versus a SC buyer. For SPRs who own no other property, ABSD is 5% on the first private purchase.
Do new launch shoebox units still exist in 2026?
New launch projects with shoebox units do still exist in 2026, but they are less common than in the 2010–2015 period. URA’s 2023 tightening of average unit size requirements to 85 sqm makes it harder for developers to build a project dominated by sub-500 sqft studios. Developers now typically include a small proportion of 1-bedroom studios (sometimes just exceeding 500 sqft) alongside larger 2- and 3-bedroom units, balancing their development mix to comply with URA guidelines while retaining some compact-unit appeal. Buyers seeking new launch shoebox units should check whether units listed as “1-bedroom” or “studio” fall above or below the 500 sqft threshold, as some are marketed as shoebox but technically exceed it.
Is it hard to sell a shoebox apartment when I want to exit?
Resale liquidity for shoebox apartments depends heavily on location and market conditions. Well-located units near MRT interchanges in RCR and CCR districts , where rental demand is consistently strong and the buyer pool includes both investors and singles buying for own stay , tend to sell within a reasonable timeframe. Shoebox units in OCR suburban estates without MRT connectivity can be harder to sell, particularly in a rising interest rate environment when investor demand retreats. Buyers should research recent transaction volumes for comparable units in the same development or district before purchasing, and factor in a holding period of at least five years to absorb transaction costs.
Can I use my CPF to buy a shoebox condo?
Yes, subject to the standard CPF usage rules for private properties. CPF Ordinary Account funds can be used for the downpayment and BSD on a shoebox condominium as long as the remaining lease covers the youngest buyer to age 95 (for leasehold units). ABSD cannot be paid with CPF , it must be settled in cash. The CPF Withdrawal Limit (capped at the Valuation Limit × applicable percentage) may restrict how much CPF you can use if the property’s bank valuation is lower than the purchase price. Your solicitor will calculate the exact CPF usable amount during conveyancing.
What is the minimum unit size for new private condos in Singapore now?
URA does not specify a minimum unit size for individual units but requires that new private residential developments achieve an average unit size of at least 85 sqm across the project (as of 2023 guidelines). This means a developer can still include a small number of studios below 50 sqm, but only if the overall average across all units in the project remains at 85 sqm or above. In practice, this significantly constrains the proportion of sub-50 sqm units in any new launch. Some inner-city commercial-residential mixed developments and serviced apartment developments are subject to different rules and may still offer very small units in a different legal format.
Is a shoebox apartment good for own-stay in Singapore?
It depends entirely on your lifestyle and stage of life. For a single professional working long hours who treats the apartment primarily as a base to sleep and store essentials, a well-designed 400–500 sqft studio near an MRT station can be entirely adequate , and significantly more affordable than a standard 1-bedroom at the same location. However, couples, professionals who work from home, or buyers who entertain frequently will find a sub-500 sqft unit constraining. Storage is almost always insufficient, kitchen space is minimal, and noise from corridor traffic and thin walls in dense-unit buildings can be an issue. Buyers should visit the unit at different times of day and assess ceiling height, natural light, and ventilation carefully before committing.
📚 Related LovelyHomes Articles
- ABSD Singapore 2026: Complete Guide to Additional Buyer’s Stamp Duty
- Singapore Property Investment Strategy 2026: Rental Yields, Capital Gains & Net Returns
- Freehold vs Leasehold Singapore 2026: What Every Buyer Needs to Know
- Buyer’s Stamp Duty (BSD) Singapore 2026: Rates, Calculation & Exemptions
- Singapore Condo Resale Guide 2026: Step-by-Step Buyer’s Complete Guide
- Singapore Mortgage Refinancing Guide 2026: When to Refinance, How Much You Save
- Executive Condominium (EC) Complete Guide Singapore 2026
Supporting graphics
Original article illustrations are available below.
- Figure 1: Shoebox units (≤500 sqft) achieve a notably higher median PSF than standard or large condos in OCR, and deliver higher gross rental yields , but the elevated ABSD cost for investors significantly extends the breakeven period. Source: URA REALIS caveats Jan–May 2026.
- Figure 2: Shoebox units peaked at roughly 22% of new completions around 2012–2013 as the initial wave of sub-1,000 sqft launches completed. URA’s 2012 and 2023 rule changes progressively reduced their share. Illustrative trend; individual years may vary.
- Figure 3: The ABSD alone (S$168,000 on a S$840,000 shoebox as a Singapore Citizen’s 2nd property) equals roughly four years of gross rental income , a critical drag on investor returns that requires a long holding period to absorb. Source: IRAS; LovelyHomes calculation.