Updated 17 September 2026. An older freehold condo and a newer leasehold condo can both be sensible homes. The useful question is what you receive for the total price: usable rooms, a workable daily routine, a building you can afford to maintain and a tenure that fits your plans.
Compare the actual units before assigning a premium to the word “freehold”. If one home is larger, quieter, closer to the places you visit or in better condition, the price difference is not a clean measure of tenure alone.
Separate land tenure from building age
Freehold has no fixed lease expiry. A 99-year or 999-year interest is leasehold, even where the remaining term is very long. None of these labels tells you the condition of the roof, lifts, pipes or the interior you are buying.
For a leasehold home, check the actual lease commencement and remaining term. Do not restart the clock from the developer’s launch, your purchase, renovation or the building’s Temporary Occupation Permit. Ask your conveyancing lawyer to verify the title and relevant restrictions. SLA’s land-title search guidance explains the available title information and the need to match an address to the correct lot.
For an older freehold condo, a long ownership horizon still needs a building-maintenance budget. For a newer leasehold condo, newer finishes do not replace a title and remaining-lease check. Assess both dimensions instead of treating one as a substitute for the other.
Do not confuse tenure with the right to buy
This comparison concerns private condo choices. The word “freehold” alone does not establish whether a particular buyer may purchase a property, what approvals are needed or which taxes apply. A landed house, a strata unit and an HDB flat should not be treated as interchangeable purchases because their advertised remaining terms look similar. Confirm the property type and the buyer’s eligibility before applying this cost comparison.
Start with our title and remaining-lease checks. For the funding decision, read why freehold does not guarantee a 75% loan or unrestricted CPF. The label does not replace a lender’s offer for the exact unit and borrowers.
Make the two homes comparable
| Compare | What to establish |
|---|---|
| Price basis | Asking price, accepted offer or completed transaction, with its date. |
| Usable space | Bedroom dimensions, storage, circulation and the area taken by balconies or terraces. |
| Position | Floor, facing, privacy, nearby activity and the actual outlook. |
| Daily use | Your commute, shopping, school or care arrangements, tested from the exact block. |
| Condition | Interior works needed and the estate’s maintenance and major-work plans. |
| Funding | Bank valuation, approved loan, eligible CPF and cash needed at each stage. |
A development-wide price per square foot can hide these differences. A lower unit price is not automatically better value if much of the floor area does not serve your household. Equally, an older layout with generous rooms may be useful even if its fittings need replacement. Use our floor-plan guide to test the space before comparing headline prices.
Worked comparison: what does the higher price require today?
These are hypothetical private-condo alternatives, not advertised or transacted units. Home A is older and freehold at S$1,480,000. Home B is newer and leasehold at S$1,260,000. Assume valuations equal the prices and, solely for this funding illustration, that a lender approves a 75% loan for either purchase.
The table excludes ABSD, legal fees, renovation, moving costs and reserves. Add any applicable amounts before treating it as a purchase budget. The 75% assumption is not a statement of your loan eligibility, and the non-loan amount is not necessarily all payable from CPF.
| Item | Home A | Home B |
|---|---|---|
| Purchase price | S$1,480,000 | S$1,260,000 |
| Assumed 75% loan | S$1,110,000 | S$945,000 |
| Price not covered by loan | S$370,000 | S$315,000 |
| Buyer’s Stamp Duty | S$43,800 | S$35,000 |
| Non-loan price portion plus BSD | S$413,800 | S$350,000 |
Home A requires S$63,800 more outside the assumed loan, while the loan itself is S$165,000 larger. The S$220,000 price difference is about 17.5% of Home B’s price. That is the gap in this invented pair, not a measured Singapore freehold premium.
The BSD calculation for the first S$1 million is S$24,600. Applying 4% to the remaining S$480,000 or S$260,000 gives S$43,800 and S$35,000 respectively. These follow the current IRAS residential BSD bands, with the assumed price also being the market value.
Now obtain actual loan terms and renovation quotations. If the more expensive home leaves too little cash for necessary works or a period without income, that is a practical constraint even if you prefer its tenure. Our downpayment guide explains why available CPF, cash and borrowing must be checked separately.
The CPF test depends on the buyer as well as the lease
There is no universal rule that every property with 60 years remaining allows unrestricted CPF use, or that every shorter lease requires the same reduction. CPF considers whether the remaining lease covers the youngest buyer using CPF to age 95, alongside other housing limits. If coverage falls short, a pro-rated limit can apply. Use CPF Board’s housing-usage guidance.
For example, 55 remaining years take a 35-year-old to age 90 but a 45-year-old to age 100. This arithmetic explains why the same property can have a different lease-coverage result for different buyers. It does not establish either buyer’s available CPF amount or approved loan.
Enter the actual birth dates, purchase date, lease details, price and valuation into the CPF housing usage calculator. Do not estimate the permitted percentage by dividing the remaining lease by the years to age 95. Confirm a very short lease directly with CPF before committing. Freehold also does not remove ordinary CPF housing limits or a lender’s credit assessment.
Test the home you will live in
Write down a normal weekday for everyone moving in. Where will a child do homework? Can a desk remain set up without blocking a bedroom? Is there enough storage for a stroller, sports equipment or a helper’s belongings? Can an older family member reach the unit and common facilities comfortably?
Then inspect at useful times. Record what you actually hear and see, including access roads, drop-off activity and neighbouring buildings. A map distance or marketing description does not establish your door-to-door journey. These observations can justify preferring one unit, but should not be presented as proof that an entire tenure category is better.
Request the exact maintenance bill and information on funds and planned works. Our maintenance-fee comparison helps separate recurring contributions from one-off cash demands. The extra purchase price is only part of the commitment.
Plan the exit without assuming a rescue
Consider when you are likely to move and what the remaining lease would be then. A home with 55 years left today would have about 45 years after a ten-year hold. Recheck the future buyer’s likely funding constraints as a planning scenario, while recognising that future rules and lending decisions are unknown.
Do not make a collective sale, lease extension or rising market the condition that makes the purchase affordable. Those outcomes need their own evidence and cannot be promised by a tenure label. Freehold does not guarantee a profitable resale; leasehold does not establish a predictable annual price decline.
For an investor, compare collected rent, operating costs, financing and eventual net sale proceeds on a consistent basis. A higher eventual selling price alone does not prove a better percentage return when the initial investment was larger. For an occupier, include the value of a home that works well for the household, without disguising that preference as a forecast of appreciation.
If you may need to sell early, include the applicable Seller’s Stamp Duty in the exit budget. A long-term ownership preference does not eliminate the possibility of an earlier move.
Compare the downside in the same way
Ask what happens if you need to sell sooner than expected, a major repair contribution arrives or your income falls. Apply the same scenario to both homes. For example, a budget comparison that gives the freehold home a renovation allowance but assumes the leasehold home has no future repair costs is incomplete. Equally, do not assume a lease top-up or collective sale will fund either owner’s next move.
For a rental investment, use rent that can be supported for the particular unit and a stated period. Deduct vacancy, maintenance, tax, financing and letting costs consistently. If you have only an agent’s asking-rent estimate, label it as that and test a lower-rent case. There is no universal tenure premium or holding period at which one option must win.
What should decide the shortlist?
Keep the older freehold home on the list if its verified condition, layout, location and funding requirements suit you, and the price remains acceptable without a guaranteed resale premium. Keep the newer leasehold home if its remaining lease and funding work for your intended stay and exit, and its daily advantages are real for your household.
If either choice only works after ignoring renovation, exhausting cash reserves or assuming an en bloc payout, revisit the budget or shortlist. The stronger purchase is the one whose full trade-offs you understand and can support.
Editorial correction, 14 September 2026: removed unsupported tenure-premium and return figures, the incorrect CPF pro-ration formula and universal 60-year threshold, and speculative redevelopment claims. Corrected the BSD examples and separated lease commencement, building age and buyer eligibility.
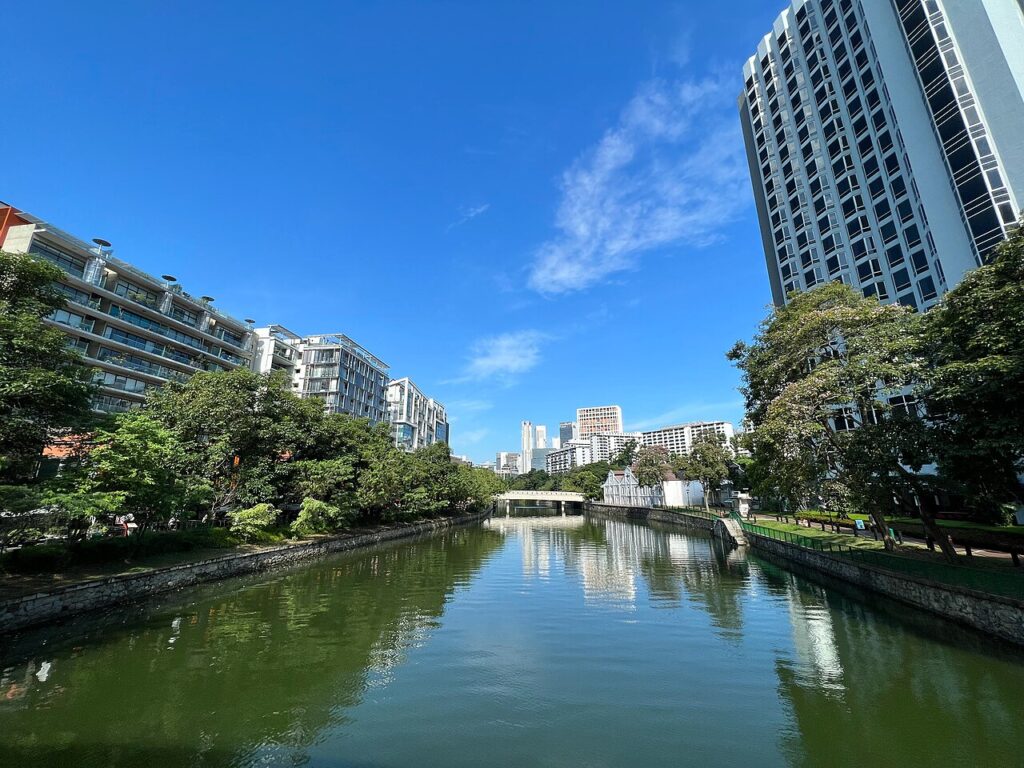
Featured photograph: Singapore River at Robertson Quay, photographed in 2022 by Wzhkevin, via Wikimedia Commons, CC BY-SA 4.0. The hypothetical homes and prices do not identify buildings in this photograph.

Consolidation update, 17 September 2026: three overlapping tenure guides now point to this comparison. Their unsupported premiums, return forecasts and funding rules are not retained. Added separate title, financing and downside checks; buyer eligibility must be established for the actual property.