
Updated 14 September 2026. Before renting out your home or keeping it after an upgrade, recalculate the property tax for the way you will use it. A bill based on living there can substantially understate the expense once you move out.
This guide focuses on that household decision: what changes in the budget, what vacancy does to cash flow and which records to check. Our property-tax rates guide contains the full current bands and rebates. Our Annual Value guide covers checking an assessment and preparing an objection.
Start with the intended use
Owner-occupier rates generally require the owner to live in the home. Letting the whole property while living elsewhere removes that treatment from the rental date. Renting bedrooms while you continue living there can retain it. A married couple can receive owner-occupier treatment for only one home between them. Check IRAS’s eligibility rules for your circumstances.
Do not assume an empty investment property qualifies just because there is no tenant. Nor should you assume every temporary absence removes eligibility: IRAS provides for temporary overseas stays for official or business purposes where the property remains your home and is not rented out.
Keep tax eligibility separate from permission to rent or retain a property. A tax calculation does not establish that your HDB, planning, mortgage or other conditions allow the proposed arrangement.
Same Annual Value, a different annual expense
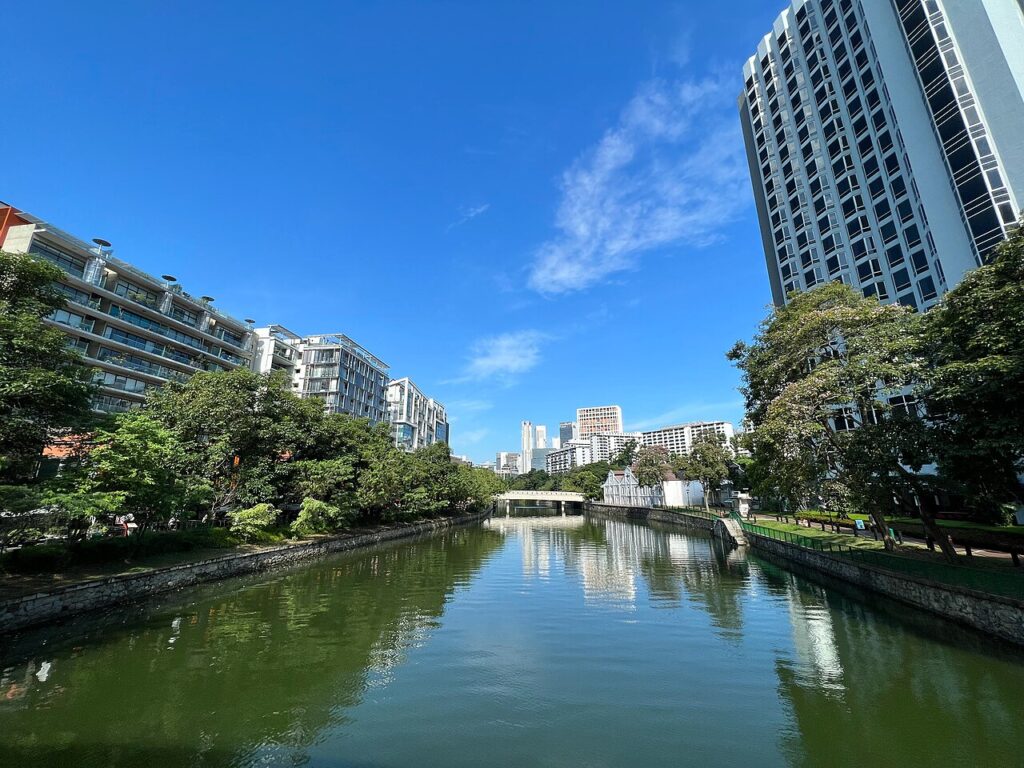
Consider a hypothetical private home with an assessed Annual Value (AV) of S$42,000. These are alternative full-year scenarios using current ordinary residential rates. They assume no change in AV or occupation during the year and exclude arrears or penalties. They are not assessments of the buildings pictured.
| Budget item | Owner lives there | Not owner-occupied |
|---|---|---|
| Tax before rebate | S$1,240 | S$6,000 |
| Applicable 2026 private-home rebate | S$124 | None |
| Full-year amount | S$1,116 | S$6,000 |
| Monthly budgeting equivalent | S$93 | S$500 |
The owner-occupier calculation is S$28,000 × 4% + S$2,000 × 6% = S$1,240. The non-owner-occupier calculation is S$30,000 × 12% + S$12,000 × 20% = S$6,000. These follow the IRAS rate tables. The monthly equivalents are planning amounts, not an assertion about an approved instalment plan.
The 2026 private owner-occupier rebate is 10%, capped at S$500; the HDB owner-occupier rebate is 15%. IRAS applies the applicable rebate automatically. See the 2026 bill guidance. Do not carry these one-off rebates into a 2027 forecast without a corresponding announcement.
In the private-home example, moving from the first full-year scenario to the second adds S$4,884 a year, equivalent to S$407 a month. This is one reason to recalculate the letting budget rather than copying last year’s household expenses.
Vacancy makes the same tax bill feel larger
Suppose the owner tests a hypothetical rent of S$3,800 a month. This is an assumed budget input, not a market-rent estimate for a named condo. Keep the assessed AV at S$42,000 in both scenarios; actual rent and AV are separate inputs.
| Item | 12 paid months | 10 paid months |
|---|---|---|
| Rent collected | S$45,600 | S$38,000 |
| Property tax | S$6,000 | S$6,000 |
| Tax as a share of collected rent | 13.2% | 15.8% |
| Receipts after property tax only | S$39,600 | S$32,000 |
Neither final row is net profit or cash left after the mortgage. Maintenance contributions, repairs, insurance, letting costs, financing and income tax still need consideration. A refundable tenant deposit is also not rent earned.
The two unpaid months remove S$7,600 of receipts while the assumed property-tax bill stays unchanged. Test whether your cash reserve can cover those months without depending on the next tenant arriving immediately. For the fuller distinction between operating income and cash after loan repayments, use the rental yield guide.
Compare the whole household after moving
Keeping the old home can add rental income, but it can also leave you paying for two homes. Put the proposed arrangement beside the alternative of selling, using consistent dates and assumptions.
- Old home: rent actually expected to be collected, non-owner-occupier property tax, ongoing bills, loan payments and a vacancy reserve.
- New home: your rent or mortgage, its ownership costs where applicable, and moving or renovation expenses.
- Cash tied up: funds unavailable because you retained the old property, including any proceeds you would otherwise have received.
- One-off costs: transaction taxes, legal fees and other costs assessed for your actual proposed purchase or sale.
Keeping a home may still fit your finances or family plans. The useful comparison is whether the additional income and flexibility justify the cash commitment and uncertainty. A positive gross yield alone does not answer that question.
Check dates when the use changes mid-year
The full-year examples above are comparisons, not a formula for a mid-year bill. Record the dates you move out, a whole-home tenancy starts or ends, and you move back. Check the assessment period and any adjustments in myTax Portal. Ask IRAS to clarify an uncertain effective date rather than applying one annual figure to the entire year.
IRAS says to notify it when moving out so owner-occupier rates can be withdrawn. When a lease ends and you move back, reapply for owner-occupier treatment. Keep evidence of the actual change; a vacant gap between tenancies does not itself show you have moved home.
If buying a property, ask the conveyancing adviser to explain the completion apportionment separately from your continuing annual budget. Check whether the seller’s bill reflects owner occupation, an older AV or adjustments that will not describe your position.
A practical file to keep before deciding
- Latest AV assessment and subsequent notices, matched to the exact unit.
- Current tax status, outstanding balance and payment arrangement.
- Intended use and dates, with the relevant eligibility checked.
- A base rental budget and a second version with a longer vacancy or lower receipts.
- A separate cash reserve for costs that continue when rent stops.
Read the finished budget as the person who must pay the bills. If it only works with full occupancy, no repairs and an unchanged rebate next year, revise the assumptions before committing.
Editorial correction, 14 September 2026: replaced outdated tax bands and inaccurate graphics, unsupported AV ranges and misleading application and timing claims. At S$42,000 AV, current full-year non-owner-occupier tax is S$6,000, not S$5,520. At S$3,800 monthly rent collected for 12 months, that tax is about 13.2% of rent. This page now focuses on budgeting for a change of use.
Featured photograph: Singapore River at Robertson Quay, photographed in 2022 by Wzhkevin, via Wikimedia Commons, CC BY-SA 4.0. No rent or tax assessment is asserted for the properties shown.
