
Every time URA releases the quarterly Property Price Index, the headlines split the private condo market into three buckets: CCR, RCR and OCR. New buyers usually learn the labels when a property agent drops them into a pitch — “this is a rare RCR freehold” or “OCR yields are better than what you’d get in CCR”. The labels shape price, rental yield, buyer profile and the resale pool you are competing with.
This guide sets out what each region is, how the 2026 numbers stack up, and where the label matters most in real buying decisions. If you are comparing condo formats as well as regions, pair this with our condo downpayment breakdown.
What the three regions mean
Core Central Region (CCR)
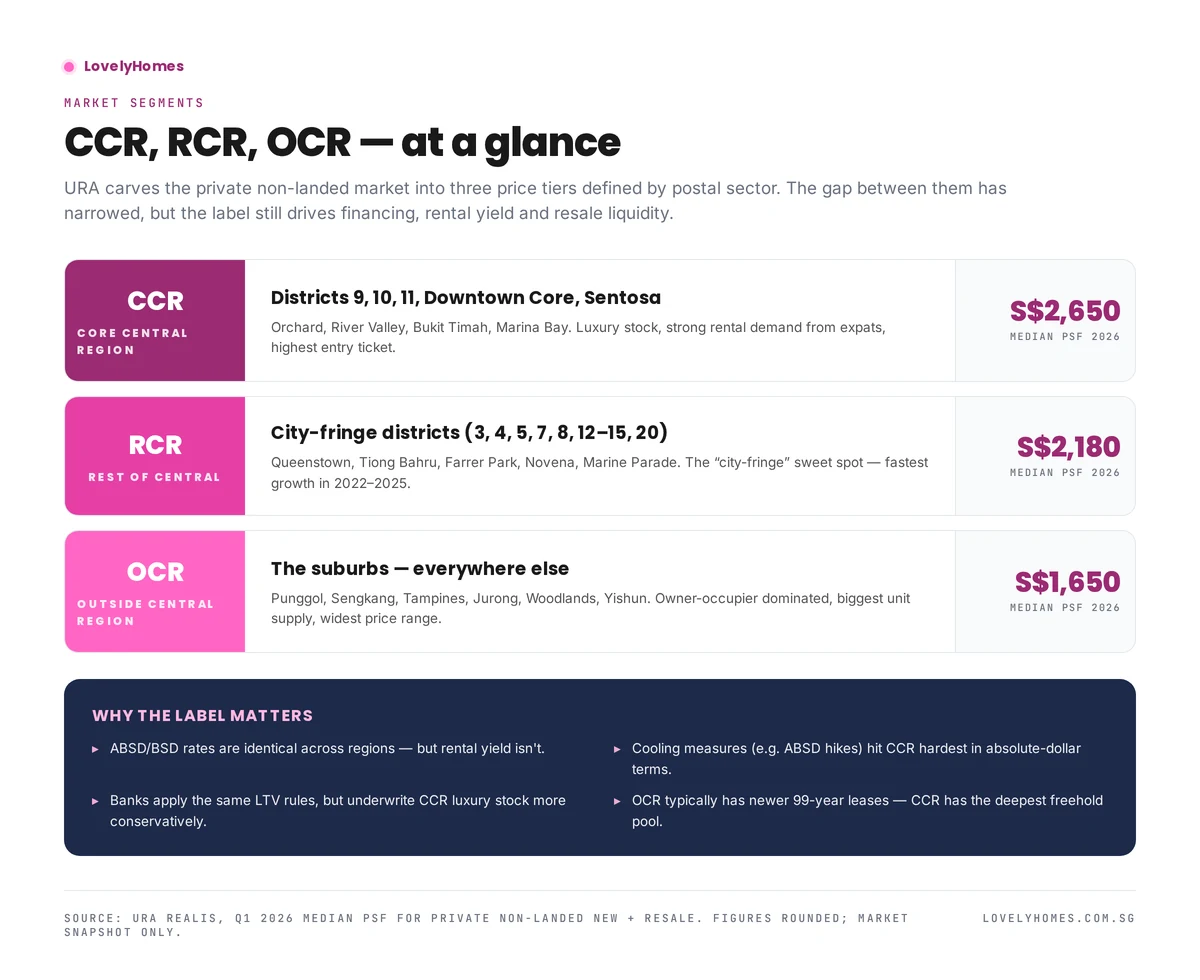
CCR covers postal districts 9, 10 and 11, plus the Downtown Core and Sentosa. Think Orchard, River Valley, Bukit Timah, Marina Bay, Sentosa Cove. The stock skews luxury: many freehold blocks, lower-density cluster homes, a deep pool of foreign-bought units pre-2023.
Rest of Central Region (RCR)
RCR is the city fringe — districts 3, 4, 5, 7, 8, 12, 13, 14, 15 and parts of 20. Queenstown, Tiong Bahru, Novena, Toa Payoh, Farrer Park, Marine Parade. From 2022 to 2025 this has been the fastest-appreciating band, thanks to new MRT lines and a rush of 99-year city-fringe launches.
Outside Central Region (OCR)
OCR is the suburbs — everywhere else. Punggol, Sengkang, Tampines, Jurong, Woodlands, Yishun, Bukit Panjang. OCR has the largest supply of new 99-year condo stock, the most owner-occupier demand, and the widest internal price range (budget 99-year next to premium integrated developments).
Where the numbers sit in 2026
| Region | Median PSF (new + resale) | Typical 2-bedder quantum | Rental yield (gross) |
|---|---|---|---|
| CCR | ~S$2,650 | S$2.3m–S$3.2m | 2.5%–3.2% |
| RCR | ~S$2,180 | S$1.6m–S$2.3m | 3.2%–4.0% |
| OCR | ~S$1,650 | S$1.1m–S$1.7m | 3.5%–4.6% |
Note the yield curve inverts the price curve: OCR delivers the highest gross yield; CCR the lowest. This is why investor pockets of OCR — near MRT interchanges, business parks — have been crowded for years.
Why the label still matters
1. Financing is region-neutral, but underwriting isn’t
ABSD, BSD, LTV limits and TDSR are identical across regions. But bank valuation and loan-amount appetite can diverge: CCR luxury units are sometimes under-valued by conservative banks, producing Cash-Over-Valuation surprises. Our COV guide explains how this works in detail for HDB, but the same dynamic shows up in high-ticket CCR resales.
2. Cooling measures hit CCR hardest in absolute dollars
A 20% ABSD rise on a S$3m CCR purchase hurts more than the same percentage on a S$1.2m OCR unit. Post-April-2023 foreigner ABSD (60%) has cooled CCR rental-to-own investment demand the most.
3. Tenure mix differs
CCR has the deepest freehold pool. OCR is mostly 99-year leasehold with a narrow freehold band around older landed enclaves. For the trade-off itself, see our freehold vs 99-year guide.
Worked example — same quantum, three regions
Imagine you have S$1.8m in purchase budget. That buys:
- CCR: A small 1-bedder (~650 sqft) in district 9 or a shoebox resale in Sentosa Cove.
- RCR: A decent 2-bedder (~750 sqft) in Queenstown, Novena or Toa Payoh resale stock.
- OCR: A generously-sized 3-bedder (~1,000–1,100 sqft) in Tampines, Sengkang or Woodlands.
For owner-occupiers, OCR tends to win on size and yield; for investors banking on capital appreciation, RCR has been the sweet spot for a decade.
Frequently asked questions
Is CCR always the safest investment?
“Safe” depends on horizon. CCR held its value better than expected through the 2014–2018 cooling-measure trough, but capital appreciation has lagged RCR and OCR from 2020 to 2025. Luxury CCR stock is also more exposed to foreigner ABSD changes.
Can a development sit across regions?
No — URA assigns each postal sector to one region. Some large projects near boundaries (for example, in Farrer Road or Redhill) feel CCR but are classed RCR. The label on the transaction determines the bucket.
Does the region change the stamp duty rate?
No. BSD and ABSD are identical regardless of region. See our BSD guide for the 2026 rate ladder.
Which region produces the best en bloc candidates?
Historically CCR and RCR, because land scarcity drives developer appetite. OCR en blocs happen, but reserve prices need to fit tighter developer margins.
This guide is for general information only and is accurate as of April 2026. Singapore property rules, taxes and cooling measures change frequently — always verify current figures with URA, IRAS, HDB or a licensed professional before committing. LovelyHomes is not a financial, legal or tax advisor.
Need a brochure, price list or professional introduction?
Contact Lin Xuan at 82222556 or Ade at 81888871 or Benn at 83218774 for the full project brochure, latest available price list, a viewing, or introductions to bankers who can help you compare home-loan rates and packages to find the best available option for your needs. If you need legal advice on a property purchase, sale or tenancy, we can also put you in touch with property lawyers.
WhatsApp Lin Xuan | WhatsApp Ade. Let us know the project or property question you would like help with. Prices and availability are subject to developer confirmation, while loan terms and approval are determined by the bank.
Lin Xuan: ONG LIN XUAN, CEA registration R069812H. Ade: CHUA MUAY MUAY (ADE CHUA), CEA registration R014252F. ERA REALTY NETWORK PTE LTD, estate agent licence L3002382K.
Benn: TAN JUN FENG, BENNEDICT (BENNEDICT TAN), CEA registration R058941E. PROPNEX REALTY PTE. LTD., estate agent licence L3008022J.